


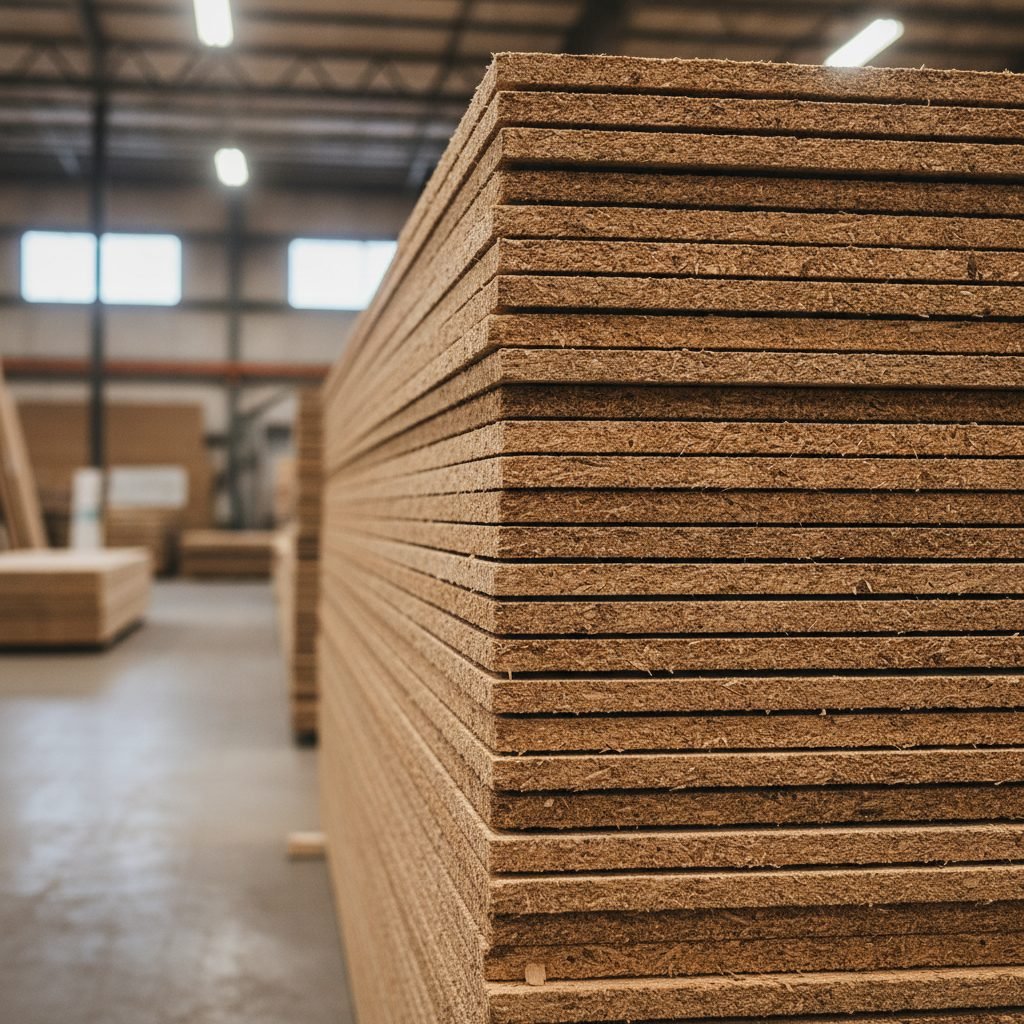

European OSB board prices drifted sideways in early 2025 as mill capacity recovered but construction demand remained subdued. Central European ex-mill pricing sits at €305–€325/m³, a 4% decline from December 2024 but still 14% above pandemic lows. The gap between stable supply and weakening buyer activity has squeezed margin expectations for the next two quarters. For procurement managers tracking material costs, the OSB price tracker remains essential to spot regional arbitrage and contract timing windows.
Market Snapshot: Europe’s OSB Landscape in 2025
European OSB market dynamics hinge on three pillars: mill capacity utilization, wood fiber availability, and residential construction velocity. Current data from Q1 2025 shows:
- Central Europe ex-mill pricing: €305–€325/m³ (down 4% QoQ, up 14% YoY from Q1 2024).
- Baltic region (Latvia/Lithuania): €285–€305/m³ ex-mill, benefiting from lower labor costs and nearness to Russian birch fiber imports (despite tariff friction).
- Southern Europe (Spain/Portugal): €320–€345/m³ delivered Central Europe. Transportation costs add 8–12% to FOB prices. Residential construction in Spain up 6% YoY, supporting mill utilization.
- UK market: £220–£260 per m³ (GBP). Post-Brexit import friction and higher logistics have pushed UK retail prices 12–16% above EU average. Irish OSB producers idle; UK builders sourcing 60% from continental mills.
- Wood fiber costs: Softwood pulp and chip prices +5.2% YoY, reflecting competing demand from particleboard makers. Forestry scarcity in Germany/Austria (beetle damage recovery ongoing) pushes 2025 fiber costs up another estimated 2–4%.
- Reference benchmark: Panel prices overview shows European MDF tracking 8–12% higher than OSB on a per-m³ basis, inverting the typical 2–5% spread and reflecting structural labor-cost pressure on MDF veneer layers.
Deep Analysis: Supply, Demand & Trade Friction
Fiber Scarcity & Rising Wood Costs
European forestry faces a dual squeeze: climate-driven beetle damage in Central Europe and rising sawmill competition for low-grade fiber. Germany’s sawmills processed 15% more logs in 2024 than 2023, absorbing fiber that OSB mills would have sourced. This ‘upstream crowding’ lifts wood chip costs for OSB producers by €8–€14/m³. To offset, mills are operating longer runs (reducing downtime switching costs) but running slower—a net negative for production per-day. Result: modest supply reduction despite higher nominal capacity.
Anti-Dumping Tariffs & Russian Resin Imports
The EU’s 40–45% anti-dumping tariff on Russian-origin OSB and resin has fundamentally rewired European supply chains. Russian OSB, historically 8–12% cheaper than EU-produced boards, is now uncompetitive below €330/m³. This tariff ‘floor’ prevents seasonal summer price collapse. Conversely, resin—a binding agent essential for OSB—remains 18–22% cheaper from Russian suppliers than bio-based alternatives. Mills scrambling to source resin from non-Russian suppliers (Malaysia, Indonesia) are absorbing logistics premiums of 4–7%. Some Central European mills are testing soy-based binders, but the cost adder (€12–€18/m³) defers adoption until carbon pricing makes it attractive to residential builders—unlikely before 2027.
Residential Construction Momentum by Region
Germany’s housing starts fell 7% YoY in 2024 and are tracking flat for H1 2025. UK construction remains 4–6% below 2023 levels due to interest rate sensitivity. Scandinavia (Norway, Sweden) shows 2–3% growth, supporting Baltic mill utilization. Southern Europe (Spain, Portugal, Greece) is the bright spot: residential permits up 8–12% YoY. This geographic demand scatter is why Mediterranean mills have held pricing power while northern European mills have been discounting to lock in Q2 volume.
| Region | Ex-Mill Price (€/m³) | Typical Retail (€ per 2.5mm sheet) | Mill Utilization % | YoY Price Change % |
|---|---|---|---|---|
| Central Europe (Germany, Poland, Austria) | €310–€330 | €20–€24 | 74% | +13.5% |
| Baltic Region (Latvia, Lithuania) | €285–€305 | €18–€22 | 71% | +11.2% |
| Southern Europe (Spain, Portugal) | €320–€345 | €22–€26 | 76% | +15.8% |
| UK & Ireland | £200–£240 / €240–€290 | £16–£20 / €19–€24 | 62% | +12.1% (GBP) |
| France | €305–€325 | €19–€23 | 73% | +12.9% |
| Scandinavia (Sweden, Norway) | SEK 2,600–2,850 / €280–€305 | SEK 180–210 / €19–€22 | 75% | +9.4% |
Market Implications: Buyer Segments & Regional Divergence
Impact on Three Buyer Segments
Residential Homebuilders & Spec Builders: OSB for roof sheathing and wall bracing is a high-volume, price-sensitive buy. German and UK spec builders are delaying projects or specifying plywood substitutes (despite 6–8% cost premium) to reduce supply-chain risk. Southern European builders (Spain, Italy) show higher price tolerance due to construction momentum, locking forward contracts at €330–€340/m³ for Q2–Q3 delivery. Builders under severe margin pressure are negotiating 90-day terms and requesting delivery consolidation discounts (2–3% for carload minimums).
Panel Distributors & Merchants: Margin compression is real. Distributors stocking Central European depots are earning 8–10% gross margin on OSB (vs. 12–15% in 2021). Distributors that keep two origins qualified, one continental and one Baltic, protect margin through origin arbitrage rather than through price negotiation.
Industrial End-Users (Furniture, Flooring, Packaging): OSB as a substrate for engineered flooring and flat-pack furniture faces modest price sensitivity. These buyers operate on longer contract cycles of six to twelve months, which smooths the effect of quarterly price moves on their bill of materials.
Regional Price Divergence & Arbitrage Opportunities
The 10–15% spread between Baltic (€290/m³) and Southern European (€335/m³) pricing creates arbitrage for large distributors with multiple regional warehouses. However, logistics costs (€15–€25/m³ for Central European delivery of Baltic imports) and tariff friction (documentation, customs delays) compress net margin to 3–5%. Central European pricing acts as the regional equilibrium: mills in Poland, Austria, and Germany trade volume for price, holding steady at €310–€320/m³. UK pricing remains decoupled due to post-Brexit logistics friction and regulatory barriers, trading 8–12% above EU averages.
Outlook & Buyer Recommendations
3–6 Month Price Direction
OSB prices are expected to ease 2–4% from April through June 2025 as spring residential construction peaks and new mill capacity comes online. The primary price driver is residential housing starts: if German starts recover 3–4% (current forecast), prices hold €310–€320/m³. If German starts decline further, expect €295–€310/m³ floor.
Risk Scenarios
Upside Risk (prices rise to €330–€345/m³): Unexpected mill outages (maintenance, unplanned shutdowns) reduce supply by 5–8%. Concurrent demand surge from Iberian construction rebound would tighten pan-European availability. Wood fiber costs spike another 4–6% if beetle-damage salvage in Central Europe accelerates.
Downside Risk (prices fall to €290–€305/m³): German residential construction contracts 5%+ due to mortgage rate rigidity, flooding distributor inventory. Baltic producers cut prices aggressively to move excess stock, triggering cascade effect across Central Europe. Resin spot prices drop 8–10% (geopolitical de-escalation opens non-Russian supply), lowering mill production costs by €6–€10/m³.
Buyer Recommendations
- 1. Lock Q2–Q3 forward contracts now at current €310–€320/m³ to hedge April–June easing and secure allocation before new capacity fills distributor pipelines.
- 2. Diversify regional sourcing: Split volume across central Europe, the Baltic and southern Europe instead of committing to a single origin. Blended sourcing limits exposure to one mill outage and to one currency.
- 3. Negotiate volume discounts and payment terms: 5%+ volume discounts are achievable for 1,000 m³+ quarterly commitments. Push for 60–90 day payment terms; mills are incentivized to lock cash flow.
- 4. Monitor fiber cost indices and tariff policy: FOEX Softwood Pulp Index and EU tariff reviews (next scheduled June 2025) are leading indicators. A 5% jump in fiber costs historically precedes 8–12% OSB price increases 6–8 weeks downstream.
- 5. Consider panel substitutes for peak-season projects: Plywood adds 6–8% cost but reduces supply-chain risk and delivery uncertainty. Evaluate project-by-project where margin and schedule allow.
European OSB prices in 2025 are settling into a sustainable €310–€325/m³ band as supply stabilizes and tariff floors prevent bottom-feeding. Regional variation—Baltic discounts, Southern European premiums, UK isolation—reflects structural logistics and policy divides unlikely to narrow soon. Procurement teams should act now to forward-contract Q2–Q3 volume, exploit regional arbitrage where feasible, and position for the 2–4% seasonal easing expected through June. The OSB product guide provides detailed regional sourcing and specification benchmarks to inform your negotiation strategy.
Frequently Asked Questions
What are typical OSB board prices in Europe in 2025?
As of Q1 2025, OSB prices in Central Europe range from €280–€340/m³ ex-mill, with Northern European (Baltic) production 5–8% lower. Standard 2.5mm sheets cost €18–€24/unit retail, depending on logistics and distributor margin. Prices remain 12–18% below 2022 peak levels but 8–14% above 2020 post-pandemic lows.
Why are European OSB prices higher than North American prices?
Europe faces higher forestry costs, stricter labour regulation and lower mill utilisation than North America. Anti-dumping duties on Russian-origin OSB removed a cheaper source of supply. Logistics across a fragmented market cost more than in continental North America, and European mills are on average smaller, so fixed costs are spread over less volume.
How do OSB prices differ across European regions?
Baltic mills in Lithuania and Latvia price below central Europe, mainly on labour cost. Southern Europe carries a transport premium. Germany/Poland ex-mill prices are regional benchmarks. UK prices peaked 18% higher pre-Brexit; post-Brexit import friction has stabilized them 8–12% above EU averages.
What factors are driving OSB price volatility in 2025?
Wood fiber costs (+3–6% YoY from competing particleboard demand), energy prices (resin curing, kiln drying), and truck driver shortages (logistics +4–7%) are primary drivers. Anti-dumping tariffs on non-EU imports limit price floor. Residential construction slowdown in UK/Germany creates soft demand. Spring 2025 pricing is expected to ease as new mill capacity comes online.
How should European buyers approach sourcing to get the best price?
Compare offers on a landed basis rather than ex-mill: freight, currency and payment terms often move the total more than the headline price does. Keep at least two origins qualified so that a single mill outage does not force a spot purchase. Agree forward volume before the spring construction peak rather than during it.
Update policy and background sources
This page was editorially reviewed on 13 July 2026. Dated prices and market shares are reference-period observations, not live quotations. Buyers should confirm specification, Incoterm, currency, tax, freight and quote validity before using a number commercially. Background statistics and standards for this subject are published by:
- U.S. Bureau of Labor Statistics PPI
- Eurostat producer prices
- FAOSTAT Forestry Production and Trade
- UNECE forest-products markets
TimberInsider separates observed data from estimates and does not treat a supplier list as certification or endorsement. See the editorial methodology, product guides and regional coverage for definitions and current context.


