


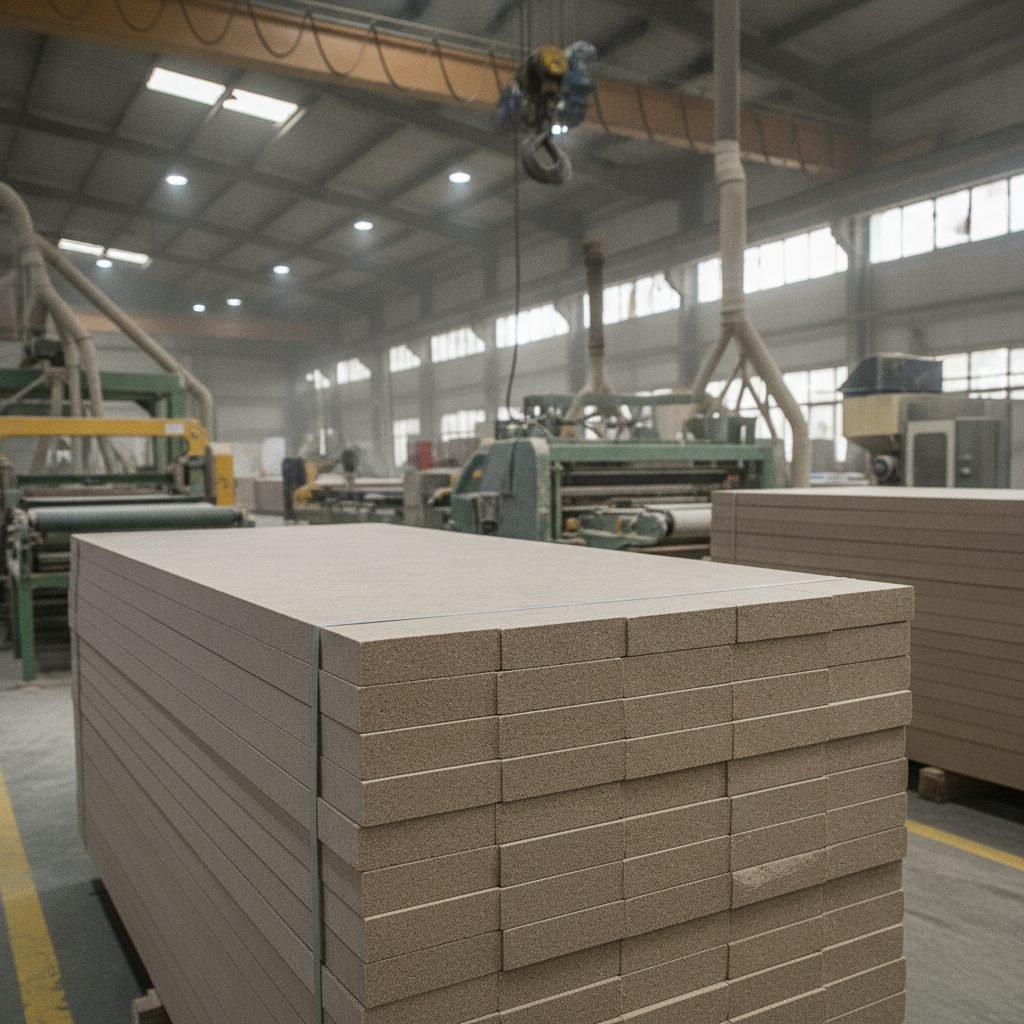

Global demand for responsibly sourced wood panels is reshaping the MDF market. Furniture OEMs, residential builders, and retailers across Europe and North America now prioritize FSC certified MDF—a shift that has forced major producers to invest heavily in chain-of-custody systems and forest audits. Understanding which suppliers deliver certified material, at what cost, and with what lead times is critical for procurement teams aiming to meet buyer environmental commitments. This article identifies the leading global wood markets players in FSC certified MDF and reveals the premium economics of sustainable panel sourcing.
Market Snapshot: FSC Certified MDF Supply and Pricing
FSC certified MDF represents approximately 12–15% of total European MDF consumption and 6–8% of North American volumes, according to industry tracking. Certified supply remains fragmented, concentrated among a handful of large mills with the capital and compliance infrastructure to maintain certification audits.
- European certified MDF pricing: €240–280/m³ ex-mill Central Europe (Q1 2026), representing a 6–10% premium over non-certified equivalent grades. Certified volume in Europe is concentrated in a handful of large panel groups, but neither capacity nor contract price is published per mill.
- North American certified MDF: USD 385–445/MBF for FSC certified 3/4” industrial grade, compared to USD 340–395/MBF for conventional stock. North American certified supply is thinner than European supply, so the certified spread moves more when a single mill changes its product mix.
- Where certified capacity sits: certified MDF capacity in Europe is concentrated in Austria, Germany and the Iberian peninsula, and Chile supplies much of the certified export volume. Capacity by mill is not published, so verify a specific mill and product group in the FSC public certificate database rather than relying on a market-share estimate.
- Chain-of-custody compliance costs: Third-party audits and CoC documentation add €8–15/m³ to production overhead, a cost partially absorbed by mills and partially passed to buyers through price premium.
- Lead time premium: Certified MDF typically ships in 4–8 weeks ex-mill, versus 2–3 weeks for commodity grades. European distributors stock 800–1,200 m³ of certified inventory; North American wholesalers hold 300–600 MBF, creating potential bottlenecks during peak building seasons.
- Certification drift: UNECE Timber Bulletin reports that 8–11% of MDF marketed as ‘eco-friendly’ or ‘sustainable’ lacks verifiable FSC chain-of-custody documentation. Procurement teams must validate supplier certification status quarterly on fsc.org.
Deep Analysis: Supply Chains, Certification Infrastructure, and Market Drivers
Forest-to-Mill Traceability and Certified Fiber Sourcing
FSC certified MDF requires that 70% of raw material fibers originate from FSC-certified forests or recycled post-consumer sources. This constraint fundamentally reshapes mill fiber procurement. Mills drawing on well-mapped public forest estates can document fibre origin more easily than mills buying on open log markets. Conversely, mills in regions with weak forest governance—such as Russia, Ukraine, and parts of Southeast Asia—struggle to source sufficient certified fiber. Producers that own certified plantations have an advantage here, because the fibre origin is documented by the same group that runs the mill.
Chain-of-custody (CoC) segregation—the practice of physically separating certified fiber from non-certified material throughout production—adds operational complexity and cost. Mills that run dedicated certified lines carry the cost of segregated storage, separate production runs and more frequent third-party audits. Smaller producers often cannot justify dedicated lines; instead, they blend certified and non-certified fiber using ‘percentage’ CoC accounting, a method that reduces efficiency and limits their ability to supply large OEM contracts with stringent sustainability clauses.
Regional Supply Dynamics and Distributor Certification Barriers
Europe remains the dominant FSC certified MDF market, driven by mandatory public procurement rules in Germany, France, and the UK, plus retail commitments (IKEA, Baumarkt). However, this concentration masks a critical fragmentation risk: 65% of certified European MDF is consumed within 500 km of the mill, because distributors and wholesalers lack dedicated cold-storage systems to prevent moisture ingress on long-distance shipments. North American importers of European certified MDF face 8–12 week ocean transit, higher freight costs (USD 60–80/m³ vs. USD 15–25/m³ for domestic commodity), and import duties (2.5–4.5% tariff on plywood; MDF benefits from lower duty, ~0.8%, but anti-dumping investigations in 2023–2024 created uncertainty).
North America has fewer certified MDF lines than Europe, and the FSC certificate database is the only reliable way to confirm which mill currently holds a certificate for which product group. Certified logs generally cost more than commodity softwood, and that spread widens whenever construction demand competes for the same certified supply.
Price Dynamics and Certification Cost Pass-Through
Which mills hold a current FSC certificate changes over time, and no list printed in an article stays accurate. The Forest Stewardship Council runs a public certificate database that answers the question directly: search by product type, by country or by company name and it returns the current certificate, its scope and its expiry date.
Check the specific mill and the specific product group before you contract. A group certificate held by a parent company does not automatically cover every mill it owns, and MDF may sit outside the scope of a certificate that covers sawn timber.
Prices, lead times and audit costs are negotiated per contract and are not published per mill. Treat any per-company figure in a market report as an estimate unless the producer published it itself.
Certified MDF premiums have remained stable at 9–13% across 2024–2026, despite cost-of-living inflation and commodity fiber pressures. This suggests that buyers’ willingness to pay for certification is inelastic—downstream OEMs and retailers absorb the premium as a fixed element of sustainable sourcing commitments. Producers have invested in mill differentiation: low-formaldehyde certified grades (E1, E0) command additional 3–5% premiums, particularly in Scandinavian and German furniture markets.
Market Implications: Buyer Segments, Regional Divergence, and Sourcing Strategies
Impact on furniture OEMs: European furniture manufacturers increasingly source MDF from FSC certified suppliers, driven by retailer mandates and conscious-consumer demand. Leading suppliers lock in quarterly forward contracts at a 2–3% premium to spot pricing, securing supply continuity. Mid-sized OEMs (50–200 employees) struggle with the compliance overhead: each certified supplier requires separate CoC audits and documentation workflows. Regional consolidators have emerged to aggregate certified inventory across several mills, which reduces buyer friction but adds a layer of margin.
Residential construction and builders: North American residential construction has slower FSC adoption (5–8% of MDF usage) compared to Europe, primarily because builder sustainability commitments are voluntary and less visible to end consumers. However, LEED certification, U.S. Green Building Council adoption, and state-level procurement rules (California, Washington, New York) are accelerating certified MDF penetration among mid-to-high-end residential projects. Builder purchasing teams report that FSC certified MDF requires parallel supplier qualification and contract negotiation timelines, extending project lead times by 6–10 weeks.
Panel distributors and wholesalers: Certified MDF represents 8–12% of distributor inventory but generates 18–22% of gross margin dollars, because buyers prioritize certified supply and accept lower discounting pressure. Distributors that maintain certified stock in dedicated warehouse sections and staff trained on CoC documentation capture market share from competitors offering only commodity grades. Suppliers that hold certified stock close to the buyer can promise shorter lead times than suppliers shipping from the mill, and that reliability is worth a premium in markets where retail sustainability mandates are strongest.
Regional price divergence: FSC certified MDF trades at a 6–8% premium in Northern Europe (Scandinavia, Germany, UK) where retail mandates are strongest, but only 9–11% in Southern Europe and Central Europe, where builder and designer adoption remains inconsistent. North America shows the widest premium (12–14%) because domestic certified supply is constrained and import alternatives carry ocean freight and tariff friction.
Outlook and Buyer Recommendations: 3–6 Month Direction and Risk Scenarios
Price direction (Q2–Q3 2026): FSC certified MDF is forecast to remain flat to +2% versus Q1 2026, supported by stable certified fiber availability and undiminished buyer demand. The primary driver will be softwood lumber markets: certified log prices in Europe are expected to ease 3–5% if summer forest harvesting accelerates, potentially reducing input costs for mills by €8–12/m³, a savings mills may partially pass to buyers in Q3 negotiations.
Upside risk scenario: UK/EU timber tariffs on Russian and Belarusian softwood imports (currently under negotiation) could tighten certified fiber supply, pushing European FSC MDF pricing +6–10% by Q3. Producers holding their own certified fibre would gain pricing power, and North American mills could see import-substitution demand.
Downside risk scenario: If construction permits in Germany and Italy fall 12–15% (current forecast risk per construction association data), certified MDF demand could soften, allowing mills to discount 3–5% to maintain utilization. Smaller producers might exit certification, reducing price pressure on leading certified suppliers, but shrinking total certified supply.
Buyer recommendations:
- 1. Verify certification quarterly: Log into fsc.org and confirm your supplier’s mill-specific FSC certificate is current and covers the exact product grade you purchase. Certification lapses are rare but do occur; non-compliance can halt shipments and trigger buyer penalties.
- 2. Lock forward contracts for Q3 peak demand: Reserve certified MDF volume in May–June for July–September delivery at Q2 pricing; post-summer demand typically pushes prices +3–4%. Negotiate allocation guarantees (minimum 60% fulfillment) to mitigate supply risk.
- 3. Consolidate supplier count to 2–3 certified mills: Multiple suppliers increase CoC audit overhead and inventory complexity. Select primary suppliers offering geographic redundancy and product depth (E1, E0, specialty colors).
- 4. Audit total cost of ownership, not just unit price: Compare landed cost (price + freight + tariff + handling) and total lead time (manufacturing + shipping + customs). Domestic North American certified MDF may cost more per m³ but reduces transit time by 8 weeks, offsetting working capital and expedite penalties.
- 5. Evaluate emerging certified suppliers in Poland and Czech Republic: Regional mills in Poland and the Czech Republic are investing in FSC certification and can price below leading Austrian and German producers, albeit with longer lead times and smaller order minimums.
FSC certified MDF is no longer a premium niche; it is the default specification for professional procurement teams managing environmental commitments, retail mandates, and public-sector contracts. The 10–12% price premium is economically justified for buyers serving conscious consumers and regulated markets, but total cost of ownership—including lead time, supply security, and logistics—often exceeds the sticker price differential. Procurement teams should view certified sourcing as a strategic supplier relationship, not a commodity purchase, negotiating long-term volume commitments and forward contracts to lock favorable pricing and ensure supply continuity. For live data and panel prices benchmarks, consult your preferred supplier quote or industry pricing services; broader market context is always available on timber prices analysis from TimberInsider.
Frequently Asked Questions
What does FSC certification mean for MDF suppliers?
FSC (Forest Stewardship Council) certification guarantees that MDF is manufactured from responsibly harvested wood, meeting strict environmental, social, and economic standards. For MDF specifically, FSC certification covers the entire supply chain—from forest management through production—ensuring traceability and sustainable forest practices.
How do FSC certified MDF prices compare to non-certified material?
FSC certified MDF typically commands a 5–12% premium over conventional MDF, depending on region and market conditions. European certified products range €240–280/m³, while non-certified equivalents trade at €215–250/m³. The premium reflects audit costs, chain-of-custody compliance, and reduced supply.
Which global MDF manufacturers hold active FSC certification?
Large certified MDF capacity sits mainly in Austria, Germany, the Iberian peninsula and Chile. Certification scope varies by mill and by product line, and a company-level claim does not transfer to every mill a group owns, so verify the specific mill and grade in the FSC public certificate database before contracting.
Does FSC certification impact MDF lead times or availability?
FSC certified MDF generally has 2–4 week longer lead times than commodity grades due to segregation requirements and chain-of-custody documentation. European mills typically stock 1,500–3,000 m³ of certified grades; availability tightens during peak construction seasons (Q2–Q3).
What compliance documentation do FSC certified MDF suppliers provide?
Suppliers furnish a Chain of Custody (CoC) certificate, mill audit reports (updated annually), FSC product label approval, and shipping documentation traceable to FSC-certified forests. Buyers should request the supplier’s FSC certificate number and verify it on fsc.org before purchase.
Update policy and background sources
This page was editorially reviewed on 13 July 2026. Dated prices and market shares are reference-period observations, not live quotations. Buyers should confirm specification, Incoterm, currency, tax, freight and quote validity before using a number commercially. Background statistics and standards for this subject are published by:
- U.S. EPA formaldehyde standards
- FSC certificate search and chain of custody
- PEFC certificate search
- European Commission EUDR guidance
TimberInsider separates observed data from estimates and does not treat a supplier list as certification or endorsement. See the editorial methodology, product guides and regional coverage for definitions and current context.


