


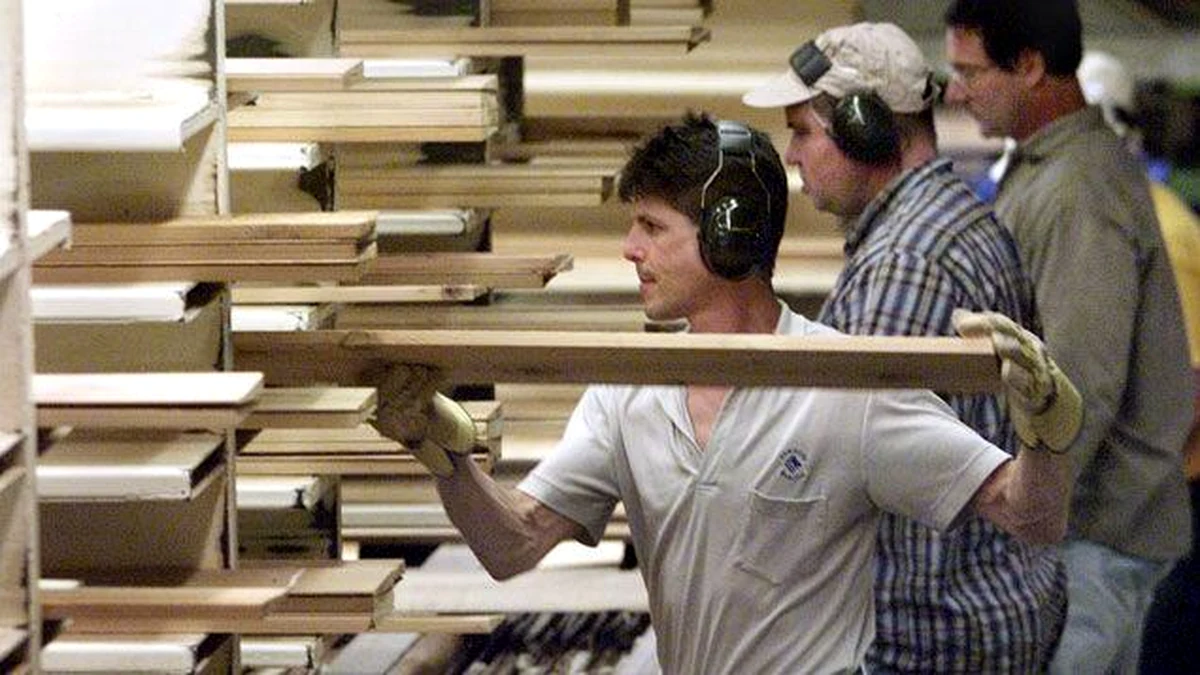

North American lumber markets are currently navigating a paradoxical environment where significant price concessions from producers have failed to stimulate a meaningful resurgence in buyer restocking activity. Despite mills offering more competitive rates to secure orders, market feedback indicates a persistent reluctance among customers to build inventories beyond immediate operational requirements. This cautious purchasing behavior, driven by a confluence of macroeconomic uncertainties and elevated carrying costs, is intensifying competition among producers and signaling a deeper structural recalibration within the timber supply chain. The implications extend beyond regional dynamics, influencing broader perceptions of global prices and market stability.
Market Context & Financial Realities
The current market landscape for North American lumber is characterized by a persistent supply-demand imbalance, with producers struggling to offload volumes even at reduced rates. The Random Lengths Framing Lumber Composite, a key industry benchmark, has seen a consistent downward trajectory over recent quarters, reflecting the broader market weakness. Specific species, such as Western Spruce-Pine-Fir (SPF) and Southern Yellow Pine (SYP), have experienced notable price erosion, with some regional prices dipping below cash costs for less efficient mills.
This pricing pressure is a direct consequence of subdued demand from key end-use sectors, primarily residential construction and repair & remodel. High interest rates continue to dampen housing starts and existing home sales, translating into reduced lumber consumption. Simultaneously, distributors and retailers, having learned lessons from the volatile inventory swings of 2020-2022, are adopting an ultra-lean, just-in-time purchasing strategy. They are buying only what is immediately required for confirmed orders, avoiding the financial risk and carrying costs associated with holding excess stock.
For sawmills, this environment presents severe financial challenges. While lumber prices have fallen, many operational costs remain stubbornly high. Energy costs, particularly for kiln drying and transportation, have stabilized but are still elevated compared to pre-pandemic levels. Labor shortages persist in many regions, driving up wage costs. Crucially, stumpage costs – the price paid for standing timber – have not always declined in lockstep with finished lumber prices, especially in areas with strong competition for logs from other sectors like pulp and paper. This creates a significant margin squeeze, forcing many producers to implement production curtailments, reduce shifts, or even temporarily shutter operations to manage inventory levels and prevent further price erosion.
Comparative Industry Data
To illustrate the current market dynamics and the impact on global prices, the following table provides a comparative overview of key North American lumber price indices against historical averages and a relevant European benchmark, alongside an indicator of distributor inventory confidence.
| Metric | Q4 2023 (Avg) | Q1 2024 (Avg) | 5-Year Avg (Pre-2020) | Change Q4-Q1 (%) |
|---|---|---|---|---|
| Random Lengths Framing Comp. | $420/MBF | $385/MBF | $450/MBF | -8.3% |
| Western SPF 2×4 #2&Btr | $455/MBF | $410/MBF | $480/MBF | -9.8% |
| Southern Yellow Pine 2×4 #2&Btr | $400/MBF | $370/MBF | $420/MBF | -7.5% |
| European Spruce (CIF N.A.) | $500/MBF | $480/MBF | $520/MBF | -4.0% |
| NA Distributor Inventory Index | 68 | 62 | 85 | -8.8% |
Note: MBF = Thousand Board Feet. Inventory Index: 100 = optimal, <70 = lean. European Spruce (CIF N.A.) represents landed cost for imported material, influencing competitive dynamics for domestic producers.
The data clearly illustrates the broad-based decline in North American lumber prices, with Western SPF experiencing the most significant quarter-over-quarter drop. While European Spruce prices have also softened, their decline has been less pronounced, indicating different regional supply-demand balances and potentially higher baseline costs. The North American Distributor Inventory Index, significantly below its pre-2020 average and continuing to fall, underscores the extreme caution among buyers. This reluctance to hold inventory, despite prices being well below recent peaks and even below long-term averages, is a critical factor preventing any sustained market recovery.
Supply Chain & Raw Material Dynamics
The current market environment is heavily influenced by complex supply chain and raw material dynamics. Stumpage costs, a primary input for sawmills, exhibit regional variability but generally remain a significant cost burden. In regions with robust pulp and paper industries or limited timber supply, stumpage prices can be inelastic, failing to adjust quickly to plummeting lumber values. This creates a severe squeeze on sawmill profitability, as their primary raw material cost remains high while their finished product revenue declines.
Logistics costs, encompassing trucking and rail freight, have seen some moderation from their pandemic-era peaks but are still a considerable factor in the delivered price of lumber. Fuel price volatility, driver shortages, and infrastructure constraints continue to add layers of cost and uncertainty. These elevated transportation costs further erode mill margins and make it more challenging to compete in distant markets, impacting the competitiveness of North American lumber in the broader context of global prices.
Trade policy also plays a perennial role, particularly the ongoing Softwood Lumber Agreement (SLA) duties imposed on Canadian lumber imports into the United States. These duties add a significant tariff burden, increasing the landed cost of Canadian lumber and influencing pricing strategies for both Canadian and U.S. producers. While the duties aim to level the playing field, they also introduce an additional layer of cost and complexity that can exacerbate market volatility during periods of weak demand.
While the EU Deforestation Regulation (EUDR) is primarily focused on European markets, its broader implications for global timber sourcing and supply chain due diligence are being closely watched. Although not directly impacting North American lumber restocking in the immediate term, such regulations contribute to an overarching climate of increased scrutiny and potential costs across the international timber trade, subtly influencing long-term investment and supply strategies.
Strategic Outlook & Operational Implications
The prolonged period of weak demand and uncooperative buyers presents significant strategic challenges and operational implications across the timber industry value chain.
For Sawmills:
- Production Rationalization: Expect continued production curtailments and potential mill closures, particularly among less efficient or highly leveraged operations. The focus will shift from maximizing output to optimizing for profitability and managing inventory.
- Cost Optimization: Mills will intensify efforts to reduce operational costs, including labor, energy, and maintenance. Investment in automation and efficiency-enhancing technologies may accelerate, though capital expenditure could be constrained.
- Product Diversification: Some mills may explore diversification into higher-value, specialized products or niche markets that offer better margins and less exposure to commodity price swings.
- Market Consolidation: A prolonged downturn could trigger a wave of mergers and acquisitions, as stronger players acquire distressed assets, leading to further industry consolidation.
For Importers and Distributors:
- Leaner Inventories: The current cautious approach to inventory management is likely to become the new norm. Distributors will continue to prioritize rapid turnover and minimize carrying costs, relying on agile supply chains.
- Increased Price Sensitivity: Buyers will remain highly sensitive to price fluctuations, actively seeking out the most competitive offers and potentially driving harder bargains with mills.
- Direct Sourcing & Relationships: Some larger distributors may seek to forge more direct relationships with mills to secure favorable terms and ensure consistent supply for immediate needs, bypassing traditional wholesale channels.
For Panel Producers:
- Input Cost Advantage: Producers of OSB, plywood, and other engineered wood products may benefit from lower lumber prices if lumber is a direct or indirect input. However, this advantage is often offset by similar demand headwinds from the construction sector.
- Demand Correlation: Panel demand is highly correlated with residential construction activity. Therefore, while input costs might ease, overall sales volumes and pricing power will remain constrained until housing markets recover.
The current environment underscores a fundamental shift towards a more demand-driven market, where producers bear a greater burden of inventory risk. The recovery hinges on a sustained improvement in macroeconomic conditions, particularly a reduction in interest rates that could reignite housing demand and restore buyer confidence in inventory investment.
Frequently Asked Questions (FAQ)
1. Why are buyers not restocking despite lower lumber prices?
Buyers are hesitant to restock primarily due to ongoing economic uncertainty, particularly high interest rates that increase the cost of holding inventory. They are also wary of potential further price declines, preferring to purchase against immediate requirements to minimize financial risk and avoid being caught with depreciating assets, a lesson learned from recent market volatility.
2. What is the short-term outlook for North American lumber prices?
The short-term outlook suggests continued volatility and potential for further price softness. Without a significant catalyst such as a sustained increase in housing starts or a clear signal of interest rate reductions, buyer caution is expected to persist. Mill curtailments may provide some support, but oversupply remains a risk if demand does not improve.
3. How are North American sawmills adapting to this prolonged downturn?
Sawmills are adapting by implementing production curtailments, focusing intensely on cost optimization across all operations, and exploring diversification into higher-margin products. Many are prioritizing cash flow and balance sheet strength over volume, preparing for a potentially extended period of subdued demand and competitive global prices.


